
Straight From Stern - October 2026
From the Desk of Steve Stern, CFP®

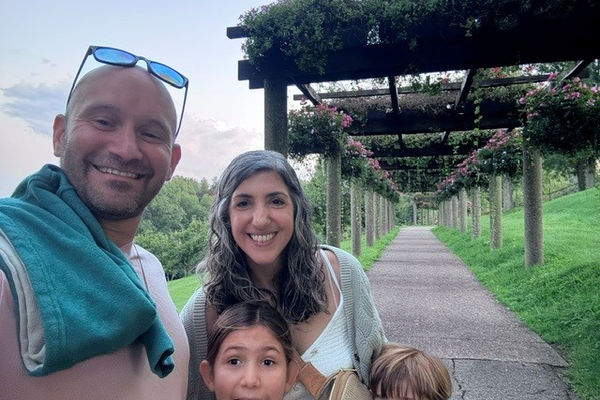


Time continues to fly by. As summer came to an end our family took a trip up to Beaver Falls, PA to visit my wife's family and celebrate the end of an era. Her Grandfather owned several clothing and shoe stores (Wolf's and Enelowe's Shoes) which he passed down to her Uncle Bobby. Bobby was retiring and the shoe store was closing down so we gathered as a family to visit the stores one final time.
On the way we spent several nights at Oglebay Resort in Wheeling, WV. We were stunned at how beautiful the resort was and how many activities there were to do. On-Site were several restaurants, 4 golf courses, a zoo, their own hydroponic garden to grow greens for the menu, lake activities, hiking trails and much more. Most impressive was the beautiful flowers throughout the nearly 2,000 acres. It was a great end to the summer.
Market Performance — September
Source: StockAnalysis.com, verified October 2, 2026
Key Benchmarks: S&P 500: 7,666.45 | 10-Yr Treasury: 5.17% | Fed Funds Rate: 3.75% - 4.00%
September's Winner: Commodities
Commodities led all asset classes in September 2026 with a return of +0.33%. Commodities also leads year-to-date at +36.98%. Energy and agricultural commodities benefited from geopolitical supply concerns and stronger-than-expected global demand data during September, particularly as manufacturing activity showed resilience across key regions. This broad-based rally reflects real economic tailwinds—not speculation—giving investors who maintained commodity exposure a meaningful boost to their diversified portfolios.
September's Laggard: Gold
Gold was the laggard in September 2026 with a return of -6.75%. Year-to-date, Bonds trails at -5.35%. Gold typically strengthens when investors seek safe-haven assets, but a resilient economic outlook and higher interest rates made other fixed-income and equity opportunities more attractive relative to non-yielding bullion. Patience with gold positions remains valuable because its diversification benefits often materialize during periods of financial stress, regardless of shorter-term price movements—this is not the time to abandon your long-term allocation framework based on monthly performance.
What We're Watching
As we entered 2026 I've been discussing the optimistic narratives that should propel this bull market into the late 2020's. These included roaring consumer spending due to the retiring baby boomers and their appreciated home values and stock portfolios, the new industrial revolution spending on AI, data centers, the space economy, robotics and defense spending and the business friendly policies of the current administration. These narratives continue to hold but we entered and remain cautious in 2026 due to several other historically risky catalysts:
* Mid-term elections years are the weakest of the 4 year presidential cycle (particularly May-October). The average correction is 17%.
* New Fed Chairs are often tested by the bond market leading to corrections greater than 10%.
* Mega IPO's from SpaceX, Anthropic and OpenAI which could suck liquidity from the markets.
* Record Margin Levels signal over extended risk taking
These risks continue to ring true as the market has barely gone up since May. In addition, under the hood of the largest companies, less than 25% of companies in the New York Stock Exchange are above their 50 day moving average and less than 40% are above their 200 day average. This is often a sign that the market is unhealthy and being propped up by the largest companies. This can be resolved with a correction or a rebound by the laggards.
At the moment all eyes are on the Iran War and the Strait of Hormuz. If the bond market feels that the oil situation continues to be inflationary, the long term interest rates will continue to rise, putting stress on the least profitable companies and stymie growth. This will also pressure the federal reserve to raise short term interest rates which will slow growth.
So what does this mean? For now we are in wait and see mode to see how this resolves. We are prepared to be more conservative but also eagerly awaiting what I believe will be the next phase. An accord between the US Treasury Dept and the Federal Reserve to stimulate and turn on the printing press. What this means is that assets will continue to rise (stocks, home prices, etc) while inflation remains elevated and potentially lead to a speculative boom into 2027.
Time will tell.

As always, if you are concerned or just want to have a conversation with a friendly human, call Steve at 443-812-5459 or email him to set up a meeting at sstern@abel-financial.com. You can also use our “Schedule a Meeting” link below.
Warmly,
Steve Stern, CFP®
Abel Financial | sstern@abel-financial.com
Disclaimer: This newsletter is for informational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Please consult with a qualified financial advisor before making investment decisions.

Comments